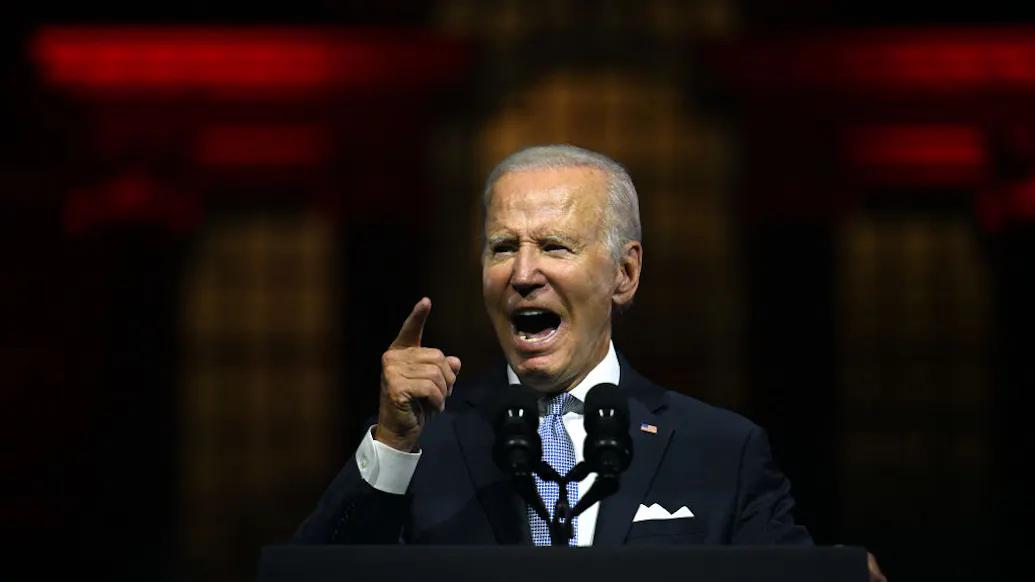
The Biden administration pushed several major banks to hamstring conservative nonprofits and retailers of MAGA-branded merchandise, a new government watchdog report finds.
The Office of the Comptroller of the Currency examined nearly 100,000 complaints and about 420,000 pages of bank documents and found that nine major banks, including Bank of America, Citibank, and Wells Fargo, denied service to customers whose political or religious affiliations caused “reputation risk,” a vague term propagated by Biden regulators.
Federal debanking efforts began in earnest under President Barack Obama, whose Justice Department in 2013 launched “Operation Choke Point,” ostensibly an effort to target “companies believed to be at a high risk for fraud and money laundering.” In reality, Choke Point involved government officials pressuring banks to cut ties with firearms dealers and other businesses the Obama administration deemed intolerable. The Biden administration continued its debanking efforts with Operation Choke Point 2.0, an effort to target cryptocurrency industry, firearms, and religiously affiliated businesses.
Wednesday’s report shows how banks responded to the Biden administration’s debanking push.
PNC denied a line of credit to a media company in 2021, citing concerns about the political views of its owners. “I think it becomes really difficult to justify aligning ourselves with a company whose owners have built very public personas around opinions very contrary to PNC’s beliefs/values,” one PNC employee wrote.
TD Bank flagged a Christian health care sharing ministry, writing that its “moral and religious requirements” appeared “to conflict with TD’s values of diversity and inclusion.” In 2024, Wells Fargo staff reviewing a prospective firearms-industry client wrote that “[u]nder the Biden administration, banks could face greater supervisory pressure to move away from lending to the firearms industry.” Wells Fargo ultimately declined the business, citing a lack of potential revenue.
The coal industry also faced restrictions, with banks limiting financing for new or expanded coal mining operations and coal-fired power plants. Some even restricted financial services to companies based on how much of their revenue was derived from coal. The report said banks cited concerns about negative headlines, public protests, and the perceived reputational consequences of financing the coal industry.
The other banks named in the report were JPMorgan Chase, U.S. Bank, Capital One, PNC, TD Bank and BMO. All nine banks told the OCC they have since changed their policies, but the agency warned that the changes might not prevent a return to past practices.
“The OCC is unable to say with confidence that current policies preclude banks returning to the harmful practices discussed in this report,” the agency wrote.
JPMorgan CEO Jamie Dimon has emerged as a vocal supporter of the Trump administration’s efforts to end debanking, noting that JPMorgan and other financial institutions were strong-armed into debanking individuals by the Biden administration.
“The rules and requirements are so onerous and it does cause people to be debanked who, in my opinion, should not be debanked,” Dimon told reporters in February.
The OCC’s report found that in February 2021, small payment company owned by JPMorgan closed the account of a merchant that sold pro-Trump and MAGA products. A JPMorgan spokesman tells The Daily Wire that its “policies prohibit discrimination against customers based on political or religious views,” and that a process used by WePay, which the bank has since wound down, did not meet its expectations. “We identified it, corrected it, and the business no longer operates.”
The report also found that JPMorgan turned away small firearms makers. But a source with knowledge of the matter clarified for The Daily Wire that the bank has long provided financial services for the firearms industry. The bank did have a policy prohibiting lending to certain firearms manufacturers, the source says, but that policy has since been eliminated.
“These historical firm-wide prohibitions have been removed,” the source adds. “Client decisions are made on a case-by-case basis.”
The National Shooting Sports Foundation, a firearm industry trade group, praised JPMorgan in February for lifting that restriction.
Republican lawmakers on Wednesday cheered the release of the OCC’s report, including Ohio Rep. Jim Jordan, who took to X to catalogue the many ways the Biden administration targeted conservatives.
The Democrats:
-Debanked conservatives
-Spied on conservatives
-Censored conservatives
— Rep. Jim Jordan (@Jim_Jordan) October 14, 2026
“No law-abiding American should be debanked for their beliefs,” Rep. Andy Barr (KY) said, while Pennsylvania Rep. Dan Meuser noted that the “report exposes how far Biden-era debanking went to pressure banks to cut off Americans for their politics, faith, and lawful businesses.”
Today’s @USOCC report exposes how far Biden-era debanking went to pressure banks to cut off Americans for their politics, faith, and lawful businesses.
My Oversight & Investigations Subcommittee has exposed this overreach since our first hearing on Operation Choke Point 2.0 and in our report on Biden’s debanking of digital assets.
@FinancialCmte is working to end debanking for good. My SAFE Guidance Act stops regulators from using unofficial guidance to pressure banks, and @RepAndyBarr’s FIRM Act permanently ends the “reputation risk” standard Biden regulators used to discourage institutions from banking lawful industries like firearms and crypto.
Thank you to @USComptroller Gould and OCC for their work to expose this overreach, and I look forward to continuing our work together to ensure a future administration cannot repeat Biden’s mistakes.
— Congressman Dan Meuser (@RepMeuser) October 14, 2026
“Proof of what we knew all along — the Biden admin weaponized the federal government against conservatives and pressured private companies to do the same,” Florida Senator Rick Scott said. “This can never happen again.”