It’s one of the most common questions people have: If the economy is doing so well based on every official metric, then why are there so many anecdotal indicators — which we all see in our day-to-day lives — that Americans are struggling financially?
If the stock market is near all-time highs, unemployment is low, and everyone is extremely (one might say excessively) well-fed, then to all outward appearances, we’re doing pretty well as a country. So why are so many people complaining about food prices, the cost of living, and the difficulty of getting a job? Has everyone gone insane? Have we become a nation of whiners, unwilling to pull ourselves up by our bootstraps? Are the numbers cooked? There has to be some explanation. But no one seems interested in providing one.
Just to give you a sense of how bizarre this particular dilemma has become — at the moment, when America ranks as the single wealthiest country on the entire planet, one of our most popular homegrown genres on YouTube involves car repos. Yes, car repos.
Most of the time, in these videos, people don’t realize their car is being repossessed because they failed to make their monthly payments. The tow truck pulls up, grabs the car, and it’s gone in about 30 seconds. But every so often, the deadbeats realize what’s happening. They frantically run out into the Walmart parking lot, pants around their ankles, pleading with the guy to give them their car back. And in every case, the driver is completely unmoved by their desperate pleas.
Watch:
You can imagine why this content is popular. Obviously, it shows people at one of their lowest moments in life, which is always appealing to a certain segment of the population. It’s a self-esteem boost for a decent number of people. But if we’re being honest, part of the appeal is that, for once, deadbeats are actually suffering consequences for their actions.
They thought they could simply stop paying their car note, just like they’ve probably stopped paying rent, child support, and everything else. But in this one instance, justice arrives in the form of a tow truck driven by a guy with a million YouTube subscribers who simply does not care about their excuses. He’s looking to make some content, while also getting paid by JP Morgan or US Bank for returning their car.
He doesn’t care about anything else. And in an environment where bad behavior is constantly forgiven, this kind of video — as voyeuristic as it is — can also be refreshing to see, at some level (Also, unlike the show COPS, which goes out of its way to find white meth heads to mock, there’s clearly no hesitation here to broadcast real-life footage, regardless of the racial demographics that may be involved in these repos).
All the same, there’s no getting around the fact that, in a prosperous country, you wouldn’t expect car repos to be a particularly popular genre. This is Idiocracy-level content — the kind of video that should be leading the charts in Pakistan or Sudan, not the United States.
In particular, there’s the massive popularity of videos by Dave Ramsey, Caleb Hammer, and others. They routinely interview complete morons who have racked up tens of thousands of dollars in debt. Here’s one of them to give you an idea.
Watch:
I have to be honest — I always assumed that credit card companies had to work a little harder than this. I thought they needed to use a variety of psychological tricks to convince women to spend money they didn’t have — like reward points that you can only spend on an overpriced travel portal, or promotional APRs that leave you with a massive interest bomb at the end, or the Super Bowl ads with Samuel L. Jackson that convince you it’s cool to have a credit card.
In fact, the credit card companies didn’t need to do any of that. They’re dealing with people who don’t even understand what “debt” means. Think about that. They’re clueless about the concept of owing money to someone else. So really, all the credit card companies had to do was give women a credit limit of $8,000. And some women, like the one Hammer interviewed, apparently assume that they’re basically getting a “statement credit” or a voucher worth $8,000. It’s free money to them. In the clip, she actually called her mother to brag about her credit limit, without understanding that she was talking about her debt.
It’s an important reminder that, no matter how many dumb people you’ve encountered in your life, you’ve probably never spent any significant amount of time interacting with the absolute dregs of society. Truly, there is no bottom. There are people walking among us who are willing to admit, on camera, that they do not understand the concept of credit or debt.
Until very recently, we were importing millions more people every year — many of whom can’t speak English — who are even less informed than this. These people are getting access to credit. They’re spending it, without even realizing what they’re doing. As a direct result, the prices for everything you buy are going up.
This is an economic concept that needs some explanation because no one ever talks about it. When everyone — even complete morons who can barely dress themselves — is given access to thousands of dollars in credit, then markets immediately become very distorted. No one asks themselves, “Can I actually afford this?” Instead, they think in terms of monthly payments. Or, as in that video, they don’t think at all — they simply swipe the card, and then call their mother to brag. When this view becomes mainstream — and it has — then demand goes up, while supply doesn’t change. And as we know from the principle of supply and demand, the result is that prices increase as well.
We see this in a variety of industries, from colleges to cars. The moment the federal government made it easy to obtain student loans, tuition skyrocketed. By the same token, as banks have increased the maximum duration of auto loans — up to 96 months has become common — the price of cars has also increased. And no, I’m not making that up: dealerships are now offering 96-month auto loans, which is another way of saying 8-year loans (But they don’t want to say 8 years, because I guess that sounds too long to most people). Not only that — dealerships are bragging about these loans on social media. Here’s one example from a dealership in Houston. This was uncovered by a YouTube channel run by Marissa Van.
Watch:
Realistically, there is no way she’s going to hold onto this vehicle for 96 months. Even if she wanted to, it’s not going to happen. This car is going to get repo’d, and she’s going to appear in a YouTube video in a few months chasing after the tow truck. When that happens, her equity in the vehicle — including her $4,000 down payment and any payments she’s made up until that point — is almost certainly wasted. That’s because, when your car gets repo’d and sold at auction, it’s usually sold on the cheap so that the bank can recover the money they lent you — with a lot of fees tacked on. Her equity in the vehicle — assuming she has any by that point — is going to get wiped out.
This scenario plays out every day, thousands of times. That’s not an exaggeration. By one estimate, in 2025, more than 3 million vehicles were repossessed. That comes out to more than 8,000 vehicles per day. Those numbers, by the way, are similar to what we saw following the recession in 2009.
You’ve probably seen people like this buying a car the last time you were in a dealership. Just by looking at them, you can tell they’re not going to be able to afford the monthly payments. The car they buy is going right back to the dealership — it’s just a matter of time. But you can’t simply ignore these people, because they’re indirectly making your own vehicle much more expensive in the process.
The fact that you’ve saved up enough cash for a significant down payment, and that you’ve secured a reasonable interest rate with payments you can afford, does not really matter. You’re competing with people who have “access” to very large amounts of money they haven’t earned in the form of credit.
So if you want the car — whether you’ve saved for it or not — you’re going to pay a lot more money. This is one of the reasons car MSRPs are now so high. In just the past decade, the typical MSRP for a new vehicle has increased by roughly 46%. The average MSRP is now over $50,000, compared with around $33,000 ten years ago. It’s impossible today to find a new vehicle with a starting MSRP below $20,000. After all, if you’re a car manufacturer, why bother making a budget vehicle? Everyone’s walking into the dealership with unlimited credit. You might as well take advantage of them.
We have to be honest about the broader economic numbers that we do have — the ones that tell a much more positive story about the economy. That’s not because the numbers are necessarily accurate or illuminating, but because we need to establish some kind of baseline.
It’s true that the total debt currently held by U.S. households — as of this year — is more than $18.8 trillion. In raw dollar terms (without adjusting for inflation, wage growth, population size, or anything else), that’s more debt than we’ve ever had at any point in this country’s history.
Meanwhile, credit card debt also reached an all-time high of around $1.28 trillion in the last quarter of 2025. The debt then declined slightly in the next quarter, to $1.25 trillion, as many people paid off their Christmas shopping bills.
These are staggering numbers, but in context, you can argue they’re not as bad as they seem. If you go back to the early 2000’s, household debt was around 70% of the American GDP. Towards the end of 2007, just before the financial crisis, household debt was approaching 100% of GDP.
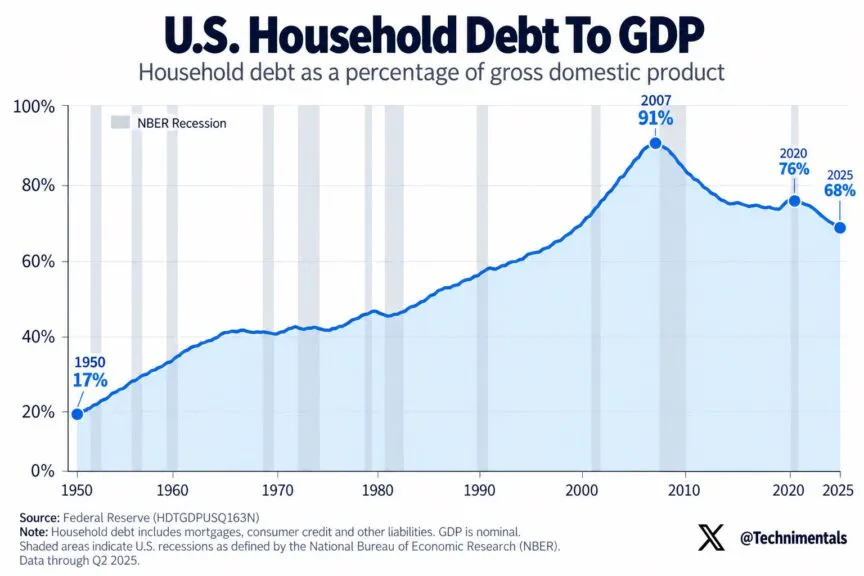
By contrast, currently household debt is only about 68% of GDP. So as a percentage of the total U.S. gross domestic product, we’re not in debt as much as we used to be. It would be much worse if we were racking up bigger debts, with a stagnant economy on top of that. So this is a good sign — although, of course, GDP is not necessarily the most important metric either. If Amazon or Microsoft have a very good quarter, the GDP will go up. That doesn’t necessarily mean that Americans will get wealthier (or have more money to pay their debts).
So there’s another metric that gets used, which is called the “Household Debt Service Ratio.” This looks at total household debt payments (including mortgage payments, car loans, and credit card debt) and measures them as a percentage of your total after-tax personal income — meaning, money you can actually spend freely. This ratio is much more important.
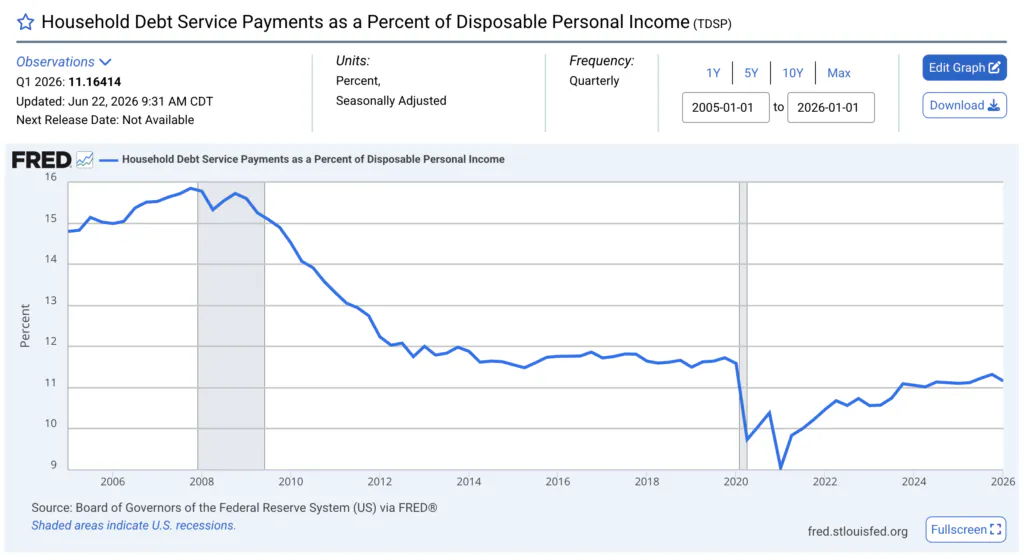
Source: Federal Reserve Bank of St. Louis
And as you can see, it was much higher 20 years ago than it is today. It peaked around 16% in 2008, and now it’s down to around 11%. If you zoom out from 1980 to 2004, the average was roughly 11% as well. So we’re spending a lot less on debt payments than we were during the financial crisis, and we’re spending about as much as we’ve been spending since 1980. Based on these numbers, there is no obvious crisis involving household debt. We’re not suddenly borrowing a lot more money to pay for cars or houses we can’t afford. And we’re not drowning in credit card debt — at least, not to an unprecedented degree.
But these figures don’t account for every kind of debt. In particular, they ignore rent payments, which are obviously a very significant household obligation (Although it’s technically classified as an ongoing obligation, not a debt). For a while, the figure also effectively excluded some forms of student loan debt, although that has changed recently. Here’s the interesting thing about student loan debt: It’s ballooning out of control right now, particularly among women.
This is yet another disastrous consequence of the feminist movement. Women have been told to attend college at any cost — including art colleges and “beauty colleges” that are basically scams — and tens of millions of women are now graduating with useless degrees and a mountain of debt. On top of that, they’ve driven up the cost of tuition for everyone else — which was already extremely high because of federally backed student loans.
More than 60% of student loan debt belongs to women at the moment. And the average student debt for women in this country now exceeds $30,000 (with black women leading the pack at $40,000). Meanwhile, the median female graduate earns around $66,000 a year after graduation, meaning half of female graduates make less than that. And here’s the kicker: the average student debt repayment among women every month is just $307.
They’ll be in debt for at least a decade, assuming they make every payment on time — which is obviously a pretty big assumption. Pew recently found that 37% of female borrowers reported defaulting on their loans, compared to just 30% of male borrowers. So the best-case scenario for these women is that they’ll be in debt for a decade. The more realistic scenario is that they’re never going to pay it off — and instead, they’re going to demand that you pay the bill.
If you look at mainstream coverage of this issue, without exception, they’ll portray women as the victims in this scenario. Here’s Time Magazine, for example:
Sahara Artiga, [30 years old], originally took out $29,000 in student loans to go toward her education at Massachusetts College of Art and Design. She started paying off her loans in 2014 after she graduated. But while she has been making monthly payments towards her loans (even during the payment pause), she still owes some $27,000 … . Women still face barriers to paying off their loans due to the gender wage gap, a lack of generational wealth and gender norms placed on women. Black women are particularly affected by student loan debt. … If you are coming from a space where you have fewer resources available, that means that you’re going to take longer to pay your loans off.
There’s the fake “gender wage gap” making an appearance along with the typical language that absolves women — particularly black women — of all personal responsibility. What nobody wants to say is that, if you’re a woman who took out $29,000 to go to the “Massachusetts College of Art and Design,” you’re an idiot who deserves everything that happens to you.
The typical starting salary for a “studio art” graduate of this school is $35,000, which is right in line with what Applebee’s will pay you to serve reheated food from the back of a Sysco truck. It’s much less than a decent bartender takes home. And the job at Applebee’s (or the bar) does not require a four-year degree that costs tens of thousands of dollars in tuition (not counting housing costs).
The problem here is not that women are discriminated against. It’s actually the opposite: They’re getting hired at rates that are clearly unjustifiable. Here’s an article from CNBC earlier this month. I saw this floating around on social media, and I couldn’t believe it was real at first. But indeed, it’s legitimate.
Women accounted for almost all of job gains in August. … Women accounted for 158,000 — or around 98% — of the 162,000 jobs added in the month, according to a CNBC analysis of data released Friday by the Bureau of Labor Statistics. Men represent the remaining 4,000 net positions added, meaning their contribution to overall payroll growth was nearly 40 times smaller. … With Friday’s report, the gap between the number of jobs held by women compared with men climbed to levels never before seen, according to Laura Ullrich, director of economic research at the Indeed Hiring Lab. “We are in the midst of a shift,” Ullrich said. “It is changing right before our eyes.”
These are truly astonishing numbers, which validate everything we’ve said in the past about the feminization of the workforce. You’re not imagining it: male workers are being discriminated against at a level that’s truly unprecedented in favor of women who have flooded into the job market.
And guess where these women are working? Do you think they’re getting hired by SpaceX to design new rockets that will add trillions of dollars in value to the economy? Actually, no, they’re getting fake jobs, particularly jobs in the “local government and education sector,” which means they’re drawing taxpayer money — your money — to indoctrinate children. Women take more than 75% of those jobs. They’re also dominating the healthcare field, taking more than 80% of the jobs there — mostly in roles like “medical support.” From the same CNBC article:
Compared with 12 months ago, the BLS found that the level of employed women has grown by more than 870,000 on a seasonally adjusted basis. The male gender has lost nearly 1.5 million employed workers over the same timeframe. Part of the recent outperformance among women could stem from what sectors are driving labor force expansion. Healthcare, considered the engine of labor market growth for more than a year, continued adding positions in August. Upwards of four out of every five workers in the industry are women. The local government and education sector roared back to life in August, accounting for 42,000 jobs — or about a fourth of the total net gain. Women hold close to three-quarters of positions related to education, training and libraries.
It’s impossible to overstate the significance of these numbers. We have become a country where, instead of aspiring to raise families, women aspire to fake jobs that don’t meaningfully contribute to society, to the economy, or anything else.
Is there anyone alive who’s looked at the state of their local government or schools and decided that the solution is to hire even more women? Is there anyone who believes it’s more fulfilling for a woman to take one of these jobs instead of raising a family?
You might ask: What exactly are women doing with this money if they’re not raising kids? Here’s a window into what that world looks like. But fair warning, it’s very grim stuff.
Watch:
I Financed $10k Worth of TATTOOS https://t.co/pIin27tygJ
— Caleb Hammer (@sircalebhammer) August 23, 2026
The easy access to credit and student loans (along with meaningless employment, in the form of fake government jobs) has led us directly to this point. Thirty years ago, people like this weren’t able to use Klarna, Affirm, or PayPal’s “buy now pay later” system. They couldn’t obtain thousands of dollars in easy credit from 20 different credit card companies. In fact, until the mid-1970s, they couldn’t get credit cards by themselves at all. Now they have near-infinite access to credit, which they’re using to drive up the costs for the rest of us — at precisely the moment they’re squeezing the job market.
I’ll note, of course, that the problem is much bigger than the morons who appear on these Dave Ramsey-style shows. Some of the most powerful institutions in this country have spent years developing products that are designed to trap their customers in debt they can’t possibly escape from. This is a quote from a lawsuit that was just filed against Robinhood in Georgia. This is from a few months ago:
Plaintiff had a brokerage account with Robinhood Derivatives, LLC and lost approximately $400,000, including fees and commissions, wagering on Robinhood’s Prediction Markets Hub in 2025 and 2026 (including on sports event contracts). … Robinhood enables customers to place gaming wagers against margin on their securities portfolios, exposing customers to the loss of their securities portfolios through unregulated and potentially compulsive gaming activities. … Robinhood insufficiently warns consumers that speculative trading against margin may expose core investment holdings and long-term stock portfolios to substantial and accelerated losses and even significant debt. … In its fiscal year ending December 31, 2025, Robinhood collected $302 million in “other transaction-based revenue,” a 260% increase from the previous year, which was “primarily driven by increased user activities in Prediction Markets and instant withdrawals.”
In other words, Robinhood is a brokerage. It’s mainly used for buying stocks. But they also allow you to use your equity to gamble on sports (and politics, and everything else). And on top of that, if you don’t want to liquidate your stocks, they’ll loan you money to gamble — with your stock portfolio as collateral. So as a hypothetical, let’s say you have $20,000 in a brokerage account. Robinhood might lend you, say, $10,000 to gamble on their prediction markets. And if you lose that $10,000, they have the right to force you to sell your stocks — at whatever price they’re currently worth — to settle the debt. This is how people are losing their life savings. We have gambling apps embedded within brokerages now.
To be clear, I’m not actually blaming Robinhood for this — at least not entirely. As far as I can tell, this lawsuit has no merit whatsoever. Federal law trumps state law, and federal law allows these kinds of markets right now (even if Georgia doesn’t). What happened here is that this guy made a series of disastrous bets, and now he’s trying to claw back his money. But the fact remains that, 20 years ago, he would’ve had to book a plane ticket to Vegas to do anything like this. Now he can do it on his phone, 24/7. And that’s a temptation that, for many people, is proving to be very difficult to resist. That’s one of the reasons we stopped doing gambling ads on this show. It’s destroying lives. That’s an objective fact.
But we can’t talk about debt — whether it’s margin debt, credit card debt, or any other kind of debt — without talking about some of the potential benefits. Obviously, not all personal debt is bad. Not every margin loan ends in catastrophe (although it’s generally a very bad idea). And yes, the availability of cheap credit has been excellent for economic growth.
To the extent people use credit to purchase assets that appreciate or allow them to live, that’s a good thing. Mortgages in particular are obviously a net positive in many different ways. And it’s also good that, if you ever need to make a large emergency expense, you can do so with a credit card — instantly, without having to liquidate any of your assets.
But the extent to which credit is available today is unprecedented. This is from a recent article in Consumer Reports:
On a recent weekday, too tired to cook, my wife and I ordered takeout from Chipotle. The food came fast, but the tab will be taking its time. Thanks to a small loan through fintech startup Zip, I don’t have to pay for the two burritos, plus sodas and sides, for the next 42 days. … Buy Now Pay Later lenders generally set a minimum amount you must spend in order to receive financing. To order Chipotle through Zip, for example, I had to spend at least $35. The company, like most lenders, requires users to pay 25 up front, and then pay down the remaining balance over four equal biweekly installments. In the case of Zip, a $1 fee is assessed per installment, meaning my installments worked out to $9.75 each. At $10, Klarna, at least for now, appears to set the lowest loan threshold. When cleaning up after our Chipotle feast, my wife and I realized we were out of paper towels, so I signed up for Klarna and, within minutes, had ordered $10 worth of paper towels from Target on a payment plan. My four installments worked out to about $2.60 each.
People are doing this all the time now — they’re addicted to buying an expensive item now and paying for it over time, even when it’s a burrito or a bottle of body wash. It works out very well for the lenders, since around 35% of customers who use these loans ultimately fall behind on their payments. And when they do, fees hit, interest comes due, and their payments explode.
This is indefensible for obvious reasons. No one should be financing a burrito. It’s true that if you are starving, you should go into debt for food. But in America, no one is starving. There are massive programs and billions of dollars of charities, school lunch programs, etc., that feed poor people. The vast majority of food stamp recipients are obese. So the people using Klarna to buy stuff like burritos or shampoo are, without any doubt, being irresponsible. It shouldn’t need to be said — at any other point in our history, it would’ve been obvious. But if you spend any amount of time on social media, you’ll find that, indeed, people are actually doing this.
@moneytalk.with.shae the link is in my B I O 🥳 stop struggling in silence & do what you gotta do! #klarna #buynow #paylater #borrow #loan ♬ original sound – 🌸 SHAE | Hey Frenn 🌸
If I deciphered that correctly, she’s putting everything on “buy now, pay later” plans, from gas to groceries. This is not an aberration. A subset of the population has become dependent on this kind of spending, which completely removes personal responsibility and planning from the equation.
That’s a big problem because, for most of its history, the United States valued notions of personal responsibility, work ethic, and frugality. That’s all gone now — and in losing that, we’ve lost a fundamental feature of American life. We’ve also driven up costs for everyone else in ways that aren’t even fully apparent right now. With just a few weeks to go until some very important elections in this country, that’s important to keep in mind.
The bill for all of this excessive, wasteful spending is eventually going to come due. These people certainly don’t think they’re going to pay it. Call it whatever you want — “democratic socialism,” racial equity, whatever — at some point, they’re going to demand a bailout at gunpoint. When that happens, it won’t matter what the GDP is, what the unemployment rate is, or anything else. At that point, which is rapidly approaching, all that will matter is whether we’ve kept these people — these leeches who only know how to consume everything in sight — as far away from power as we possibly can.